
Evaluating Dave Ramsey’s Investment Strategies Against Market Data
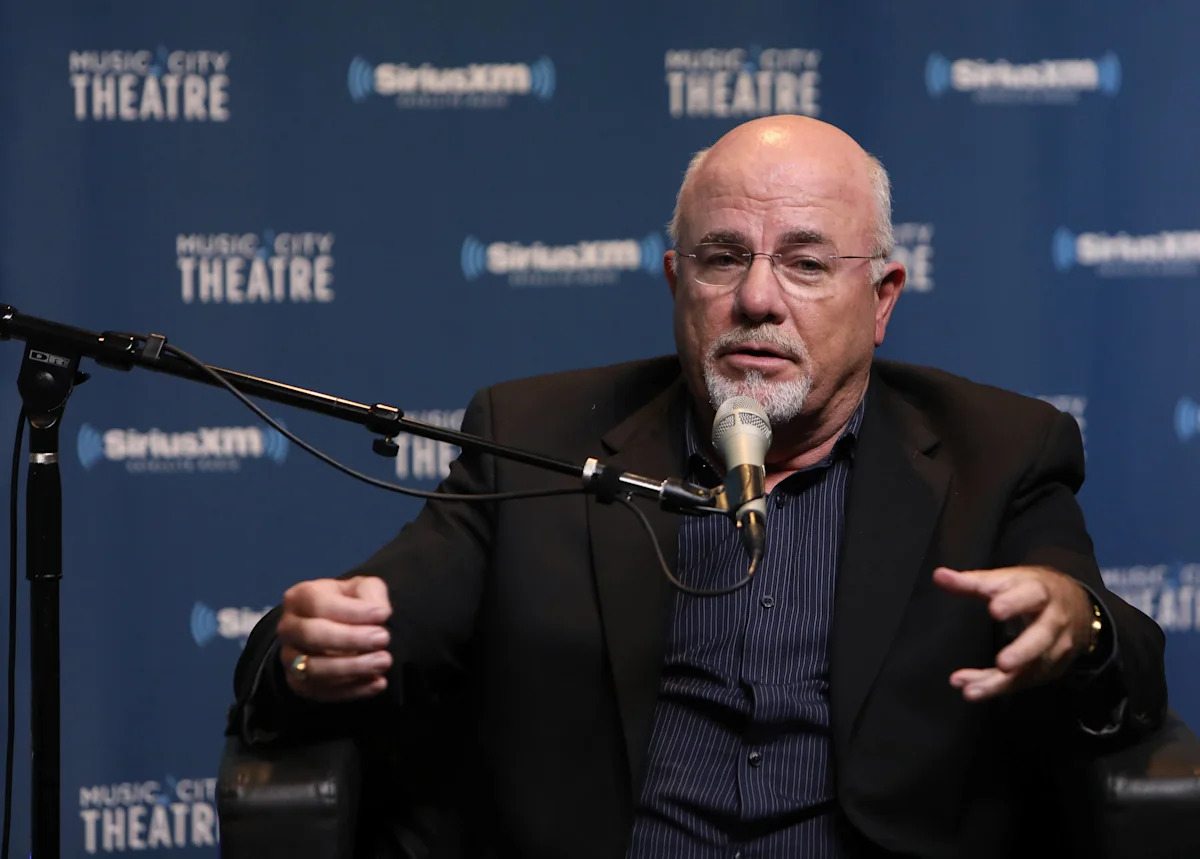
Millions of Americans follow Dave Ramsey’s financial advice, which emphasizes debt reduction, avoidance of investment fads, and reliance on mutual funds. While his approach has garnered significant support, recent analyses raise questions about the returns associated with his recommended investment strategies.
Overview of Ramsey’s Financial Guidance
Dave Ramsey’s investment philosophy encourages individuals to focus on specific types of mutual funds. He advocates allocating investments across four categories:
- Growth Funds
- Growth and Income Funds
- Aggressive Growth Funds
- International Funds
Ramsey suggests that a solid mutual fund can yield an average return of about 12% annually, provided it has demonstrated a strong historical performance.
Ramsey vs. Index Funds
In his financial education sessions, Ramsey expresses a clear preference for managed mutual funds over index funds. Unlike mutual funds that employ professional managers to select stocks, index funds simply replicate the performance of a benchmark, such as the S&P 500, often at lower costs. Ramsey has openly stated, “It’s just not that hard to beat the S&P 500.”
In a detailed explanation of his own investments, he mentioned:
“I have three investments, that’s all I have. My business, paid-for real estate, and mutual funds. I don’t play single stocks. I don’t screw around with gold. I don’t mess with Bitcoin.”
This raises a significant question: Does Ramsey’s strategy of utilizing professional fund managers actually outperform the cost-effective approach of index funds?
Claims vs. Empirical Evidence
Evaluating Ramsey’s assertions against historical market data reveals some discrepancies:
Return Expectations
Ramsey posits that a 12% annual return is a reasonable expectation grounded in historical performance. However, data from McLean Asset Management indicates that the market’s compound returns have surpassed 12% in only 5 out of 113 rolling 40-year periods, which is approximately 4% of the time.
Fund Performance Persistence
Ramsey advises picking funds with strong past performance. Yet, research from S&P suggests that fund performance has limited persistence. Specifically, not one of the large-cap funds that ranked in the top quartile from 2014 to 2018 remained in that position by the end of 2022. Furthermore, from 2020 to 2022, only 2.47% of large-cap funds outperformed the S&P 500.
Withdrawal Rates in Retirement
In discussions about retirement planning, Ramsey has claimed that an 8% withdrawal rate from a portfolio is sustainable. However, stress tests of this strategy against historical market data found that it only had about a 20% survival rate over a 30-year retirement. The widely accepted industry standard is a more conservative 4% withdrawal rate.
Critique of Cryptocurrency Investment
Since 2017, Ramsey has categorized Bitcoin as a “high-risk gamble,” advising against its inclusion in an investment portfolio. He aligns cryptocurrencies with other speculative assets, stating:
“Crypto is a currency, a digital one, and I don’t invest in currencies.”
He has often compared the crypto boom to historical fads like Beanie Babies, emphasizing the risks involved. For example, when a caller sought advice on their cryptocurrency investments while in debt, Ramsey’s response was straightforward: sell the crypto and pay off the debt.
To provide context, Bitcoin achieved an all-time high of $126,198 in October 2025, but followed this with a dramatic market correction leading into early 2026. While Ramsey’s warnings resonate with some critics of speculative investing, Bitcoin’s value remains significantly higher than when he first cautioned against it.
Conclusion
While Ramsey’s advice aims to prevent financial missteps for individuals with debt, research and historical data suggest that the effectiveness of his investment strategies, particularly regarding mutual funds and withdrawal rates in retirement, may not align with past performance trends. Though he maintains a cautious stance on cryptocurrencies, ongoing market developments continue to raise questions about the legitimacy of such assets in traditional investment strategies.
